

The Value of Membership: A Journey Toward Financial Prosperity
September 16, 2026
By Marty Pell
One of the things I care about most is helping people see how much difference a series of relatively small financial decisions can make.
A lower interest rate. A fee you no longer pay. A few hundred dollars earned instead of left on the table. A stronger credit score that gives you better options the next time you need to borrow.
Individually, those things may not seem transformational. Put them together over a year, though, and they can meaningfully change a household’s financial position.
I didn’t grow up in a family with significant financial means or a sophisticated financial playbook. I know what it is like when a few extra dollars in the monthly budget really matter. It is one of the reasons I am so passionate about what we do at Wellby Financial.
We can help people keep more of their money, pay less in interest, earn more on what they already have, and make better financial decisions.
I want our members to take advantage of their credit union membership.
Meet Marcus
 Marcus works, pays his bills, has some savings, a car loan, and credit card debt. He is doing okay, but his finances could work harder for him.
His checking account charges a monthly fee. His savings earns very little. His auto loan carries a higher rate than he may qualify for today. And while he knows his credit matters, he rarely checks it.
Marcus doesn’t need a financial miracle. He needs a few better decisions and a trusted partner to help him make them.
A Friend Points Him to Wellby
 A friend refers Marcus to Wellby. When Marcus joins and meets the referral requirements1, he earns $50, and so does his friend.
Marcus opens Wellby’s free, high-yield checking account, sets up direct deposit, and stops paying the $12 monthly fee he paid elsewhere. That is $144 a year that stays with him.
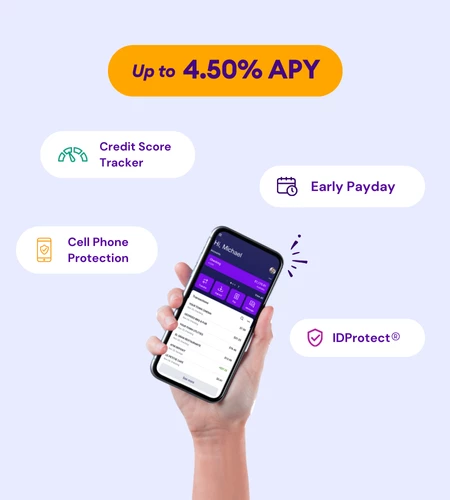
Then he learns his checking account can earn money, too. By meeting the account requirements2, Marcus earns up to 4.50% APY* on balances up to $50,000. With an average qualifying balance of $8,000, he earns roughly $360 annually.
He has gone from paying someone else for his checking account to having a checking account that pays him.
His Savings Starts Working Harder, Too
 Marcus pairs his Secure Spending checking account with a Wellby Savings Plus account.
By meeting the applicable requirements, he doubles his savings rate3. With $15,000 in savings, his qualifying balance earns 1.77% APY*, or approximately $266 annually at the current rate.
Between checking and savings, Marcus earns about $626 a year on money he already had.
Then, as Wellby celebrates its 65th anniversary, his increased engagement with his credit union earns him another surprise: a $500 special dividend4 just in time for Valentine’s Day.
He didn’t suddenly find more money to save. He made the money he already had work harder — and his relationship with his credit union created additional value.
Then Someone at Wellby Notices Something
 A few months later, Marcus visits a Wellby branch to make a deposit.
A team member notices an auto loan payment going to another financial institution and asks, “Have we ever taken a look at your car loan?”
Marcus hadn’t thought about it. It was just another bill. The team member connects him with a personal banker for a financial review.
Marcus has $25,000 remaining on his auto loan with four years left. His original rate is 11% APR*, and he qualifies to refinance at 6.5% APR*. His payment falls by about $50 a month.
That is roughly $600 back in his budget in the first year. Same car. Same paycheck. More of his money stays with him.
His Credit Becomes Part of the Plan
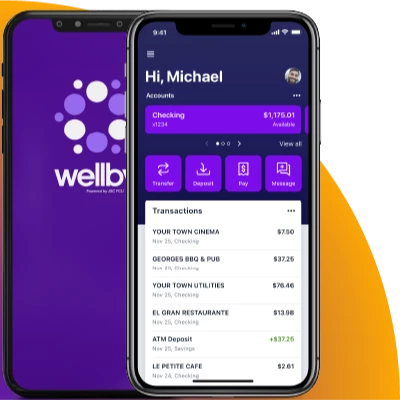
 Marcus also begins using the Credit Score Tracker5 available through his Wellby Mobile App.
Instead of learning about his score only when he needs a loan, he starts watching it regularly. As he makes payments consistently and reduces balances, his credit improves.
Stronger credit can create better options, better rates, and less money going toward interest.
That is how progress starts to compound.
And Then Life Happens
Marcus cracks the screen on his cell phone. What could have become another unexpected expense is covered in part by Cell Phone Protection6 available through his Secure Spending account, which can provide up to $600 toward eligible repair or replacement costs.
It is another benefit he may not have thought much about when he opened the account — until he needed it.
Then He Tackles More Expensive Debt
 Marcus still has about $12,000 in higher-interest credit card debt.
Instead of trying to figure it out alone, he meets with a Wellby Certified Credit Union Financial Counselor — for free — to review what he owes and what options may make sense.
Marcus uses a debt consolidation loan to responsibly replace $12,000 in debt carrying an interest rate around 24% APR* with a lower-cost option closer to 12% APR* over the same 36-month payoff period. That frees up roughly $70 a month, or more than $800 during the first year.
The right solution will be different for every member. But the principle is simple: every dollar Marcus stops unnecessarily paying in fees or interest can start working somewhere else in his financial life.
A Look at the Whole Year
 Now, add it all up.
He earns $50 through the referral program. He avoids about $144 in checking fees. His checking and savings balances generate about $626 in earnings. He receives a $500 special dividend. Refinancing his vehicle improves his first-year cash flow by roughly $600. Addressing higher-cost debt frees up another $800 or more.
That is approximately $2,720 in potential first-year value, before longer-term interest savings or the value of benefits like cell phone protection, credit monitoring, and financial counseling.
Marcus doesn’t get a raise. He doesn’t inherit money. He doesn’t win the lottery.
His money simply starts working harder for him.
But there is one more part of Marcus’ story I haven’t told you.
The Rest of the Story
 Marcus isn’t one Wellby member. He is many of them.
We created Marcus by bringing together experiences we see across our membership every day — members who have saved by refinancing, improved their credit, found better ways to manage debt, earned more on their money, and benefited from their credit union membership when life happened.
No single member’s journey will look exactly like Marcus’. That is the beauty of the collective.
Our members start in different places and have different goals, but together, their experiences show what is possible when people have the right tools, better financial options, and someone willing to help.
Marcus’ story is hypothetical, but the progress behind it is very real. I want more of it for our members.
I want our members to ask us: Could I earn more on my money? Could I lower the rate on my car? Could I consolidate my debt? Could I improve my credit? Am I paying a fee I don’t need to pay? Am I taking full advantage of my credit union benefits?
Sometimes the biggest opportunity isn’t earning more money. It is becoming more intentional with what you already have.
If Wellby can help you keep more of it, earn more from it, pay less to borrow it, and make better decisions with it, I want you to take advantage of that. That's what we mean by helping people prosper.
Marcus is a composite character created to illustrate real types of financial experiences and opportunities across Wellby’s membership. The examples and financial scenarios presented are hypothetical and illustrative. Individual circumstances, qualifications, rates, balances, savings, earnings, and results will vary. Product terms and eligibility requirements apply.
*APR = Annual Percentage Rate. APY = Annual Percentage Yield.
The APY is a percentage yield that reflects the total amount of dividends to be paid on an account based on the dividend rate and frequency of compounding for an annual period. Dividend rates and APY for the Wellby Secure Spending (checking) and Wellby Savings Plus accounts are compounded and credited monthly. Rates are variable and subject to change at any time.
1 Refer-A-Friend: Members can earn $50.00 for each new or existing eligible member (18+) who opens a Wellby Secure Spending Checking account using their referral code. Referees must keep their account open, active, and in good standing for three full calendar months, receive recurring direct deposits totaling at least $500.00 per month, and meet all other requirements. Referrers may earn up to $500.00 per calendar year (limit 10 referrals). Bonuses are paid on the fifth business day of the month following qualification. Incentives are reported on IRS Form 1099-INT. Other terms and conditions apply. Offer may change or end without notice. Registration/activation required. Other fees may apply. Click here for full details.
2 Must be at least 18 years of age to open a Wellby Secure Spending (checking) account. The Wellby Secure Spending account requires a minimum opening deposit of $100.00 and has no minimum balance requirements. The highest APY offered is 4.50% APY on account balances up to $50,000.00. Any portion of account balances exceeding $50,000.00 will earn the lowest APY offered. To qualify for the highest APY, you must complete thirty (30) combined eligible debit and/or credit card Point-of-Sale (POS) transactions of $1.00 or more that post during the applicable qualification period. A transaction is considered a POS transaction when you use your debit or credit card online, or physically at a POS register via tap, swipe, or insert. The qualification period is effective from the first day through the last day of the following calendar month and is recalculated monthly based on the prior month’s qualifying transactions. If requirements are unmet, account balances will earn the lowest APY offered. The following earnings example is for illustrative purposes only. A member maintaining a balance of at least $50,000.00 in a Wellby Secure Spending account can earn approximately $2,251.00 annually, based on an APY of 4.50%. APY is accurate as of 10/1/2024. Other account fees may apply. See the Wellby Rates and Fee Schedule in the Truth in Savings Disclosure for details.
3 Must be at least 18 years of age to open a Wellby Savings Plus account. The Wellby Savings Plus account is a tiered rate share account requiring a minimum opening deposit of $100.00 and has no minimum balance requirements. The minimum balance to obtain the stated APY for each tier is listed within the Wellby Rates and Fees Schedule in the Truth in Savings Disclosure. To qualify for the double-the-rate Bonus APY on your Wellby Savings Plus account, you must have an active Wellby Secure Spending (checking) account and complete eight (8) combined eligible debit and/or credit card Point-of-Sale (POS) transactions of $1.00 or more that post during the applicable qualification period. A transaction is considered a POS transaction when you use your debit or credit card online, or physically at a POS register via tap, swipe, or insert. The qualification period is effective from the first day through the last day of the following calendar month and is recalculated monthly based on the prior month’s qualifying transactions. If requirements are unmet, account balances will earn the lowest APY for the applicable tier. The following earnings example is for illustrative purposes only. A member maintaining a balance of at least $250,000.00 in a Wellby Savings Plus account can earn approximately $8,250.00 annually, based on a Bonus APY of 3.30%. APY is accurate as of 1/1/2026. Other account fees may apply. See the Wellby Rates and Fee Schedule in the Truth in Savings Disclosure for details.
4 The 2026 Special Member Dividend is a one-time dividend funded from available earnings. This dividend is not a promotional bonus. This special dividend is separate from and in addition to regular dividends. To be eligible, members must have a Primary Savings share account in good standing, maintain the account through the dividend payout date of February 13, 2026, and have no loans 30 days or more delinquent. Youth members who meet eligibility requirements are included. Members with accounts not in good standing (including charged-off accounts, bankruptcy, foreclosure, or repossession) or who close their Primary Savings account before the payout date are not eligible.
The dividend will be credited to the Primary Savings share account and is based on the highest engagement tier qualified for during 2025. Members may qualify through transaction activity or average daily deposit balances. Deposit-based payouts are capped at $2,000.00 per membership. Certificate of Deposit (CD) balances are excluded from calculation. To learn more about the engagement tiers and how the dividends are paid, please review the Truth-in-Savings Disclosure.
5 You will have access to your credit report and score provided your information has been verified by the credit reporting agency (CRA). Credit score is a VantageScore 3.0 based on Transunion data. Third parties may use a different type of credit score to assess your creditworthiness.
6 Special Program Notes: The descriptions herein are summaries only and do not include all terms, conditions and exclusions of the benefits described. Please refer to the actual Guide to Benefit and/or insurance documents for complete details of coverage and exclusions. Coverage is provided through the company named in the Guide to Benefit or on the insurance document. Guide to Benefit and insurance documents can be accessed through the Wellby Mobile app or online banking. Insurance products are not insured by the NCUA or any federal government agency, not a deposit of or guaranteed by the credit union or any credit union affiliate.
President & CEO